


Does setting up your company in Geneva really reduce your taxes compared with France? The answer depends on the profit made, the company’s structure and its tax situation. But the gap between the two systems deserves a close look.
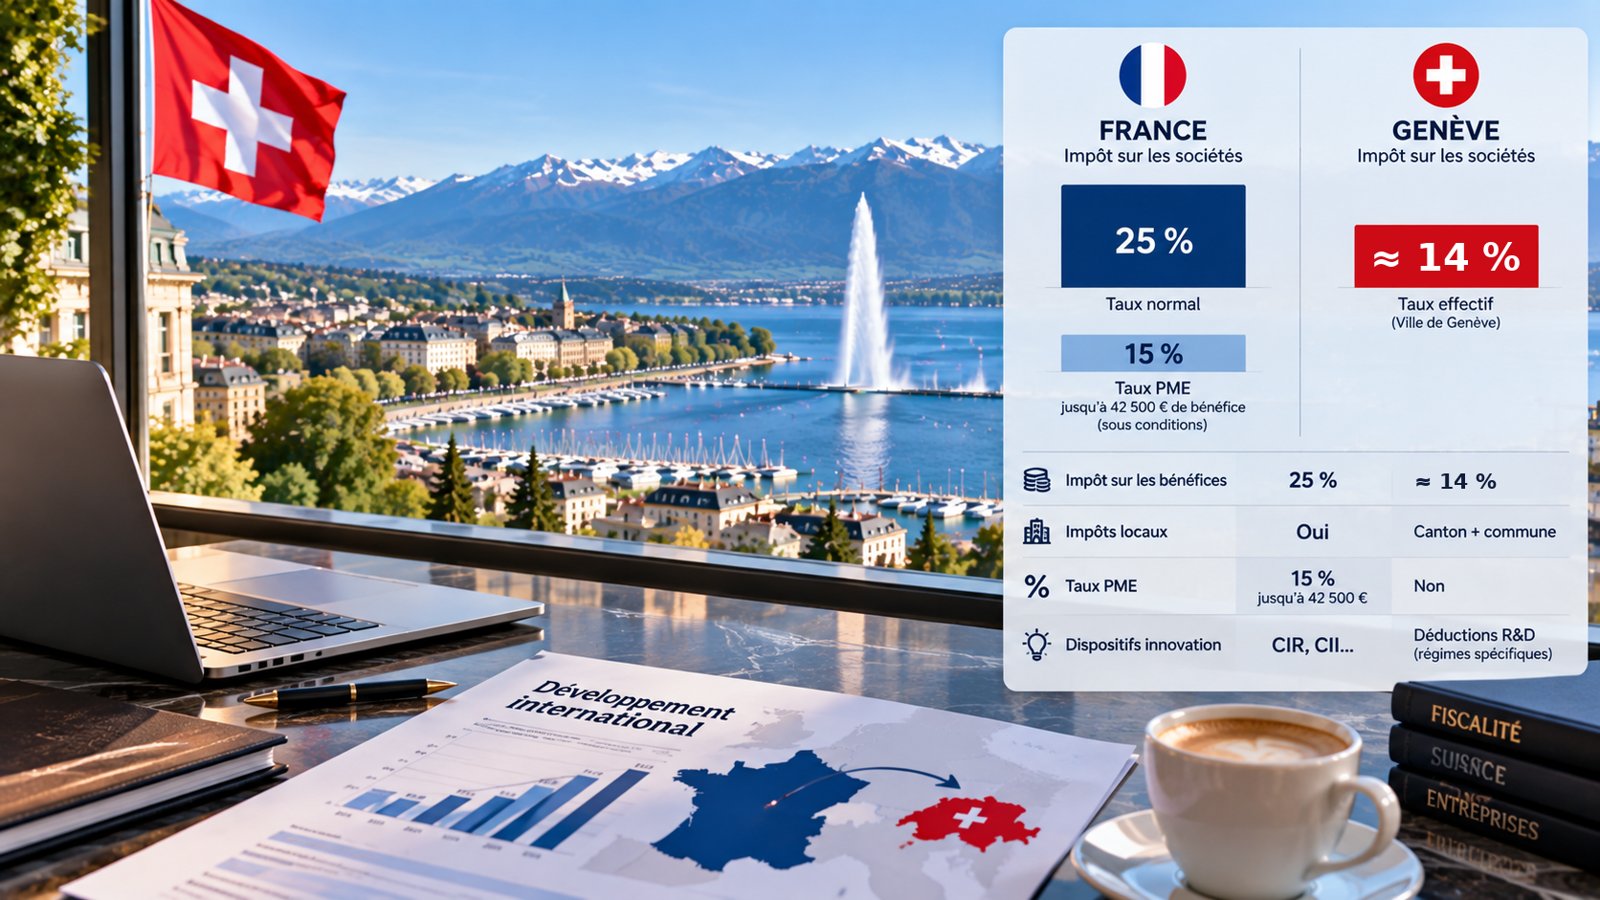
In France, the standard corporate income tax rate is 25 %. In Geneva, the combined effective tax rate on profits is around 14 % for a company based in the City of Geneva.
This difference partly explains Switzerland’s appeal for French entrepreneurs. But taxation is about more than comparing two percentages.
1. Geneva’s profit tax rate is lower than France’s
In Geneva, profit taxation combines federal, cantonal and municipal taxes.
For a company based in the City of Geneva, the combined effective rate is around 14 % (13.99% according to the cantonal tax authority). It varies slightly depending on the municipality of the registered office.
In France, the standard corporate tax rate is 25 %. Some SMEs may however benefit from a reduced rate of 15% on the first €42,500 of profit, subject to conditions (revenue below €10 million, share capital fully paid up and at least 75% held by individuals).
| Geneva | France | |
|---|---|---|
| Effective / standard rate | ≈ 14 % | 25 % |
| SME rate | — | 15% up to €42,500 |
| Federal / national tax | Included | Included in corporate tax |
| Local taxes | Canton + municipality | Separate local taxation |
For a profitable company, the gap can therefore become significant as profits grow.
2. But Swiss taxation is not just about profit tax
Comparing only 14% with 25% would be misleading.
A company based in Geneva must also take into account taxation of distributions, social security contributions, VAT, the director’s personal taxation and, depending on its activity, various specific taxes or schemes.
France also has tax mechanisms that Switzerland does not apply in the same way, including certain tax credits and reductions designed to support innovation and investment.
For a French entrepreneur, the real question is therefore less “which country taxes the least?” than “where should my company actually operate, and where should I be tax resident?”
A French company that creates a structure in Geneva without any real activity in Switzerland obviously does not automatically change its taxation. The economic substance of the establishment remains decisive.
For an SME with genuine activity in Switzerland, however, the difference in profit taxation can be an important factor when considering setting up in Geneva.
Sources: Republic and Canton of Geneva, “Profit tax from 1 January 2020” (TRAF); Service-public.fr, “Corporate tax: reduced rate for SMEs”; impots.gouv.fr, “Tax attractiveness measures”.
For more information, contact me: morgane@geneveinfos.ch


